Navigating Digital Transactions: America's Shifting Landscape of Secure Money Movement
Uma Reed · Sep 23, 2026
The Backbone of Secure Transactions in US Online Retail
US online payment processing operates through interconnected networks that connect retailers, financial institutions, and consumers across digital storefronts, and these systems handle billions of transactions each year while maintaining security standards set by regulatory bodies and industry groups. Data from the Federal Reserve indicates that electronic payments continue to grow as the dominant method for e-commerce activity, with credit cards, ACH transfers, and digital wallets forming the core options available to merchants. Payment gateways serve as the initial interface that captures customer details and routes them through verification layers before funds move to merchant accounts. These gateways integrate with processors that communicate directly with card networks and banking systems, ensuring authorization happens within seconds for most transactions. Observers note that many platforms now incorporate tokenization to replace sensitive card data with unique identifiers, which reduces exposure during storage and subsequent billing cycles. ACH processing adds another layer for subscription-based models because it enables direct bank-to-bank transfers at lower costs than card networks, and this method proves especially useful for recurring revenue streams where merchants prioritize efficiency over instant settlement. Research from industry reports shows ACH volumes rising steadily in e-commerce as platforms align these transfers with fraud screening tools that check account validity before deductions occur.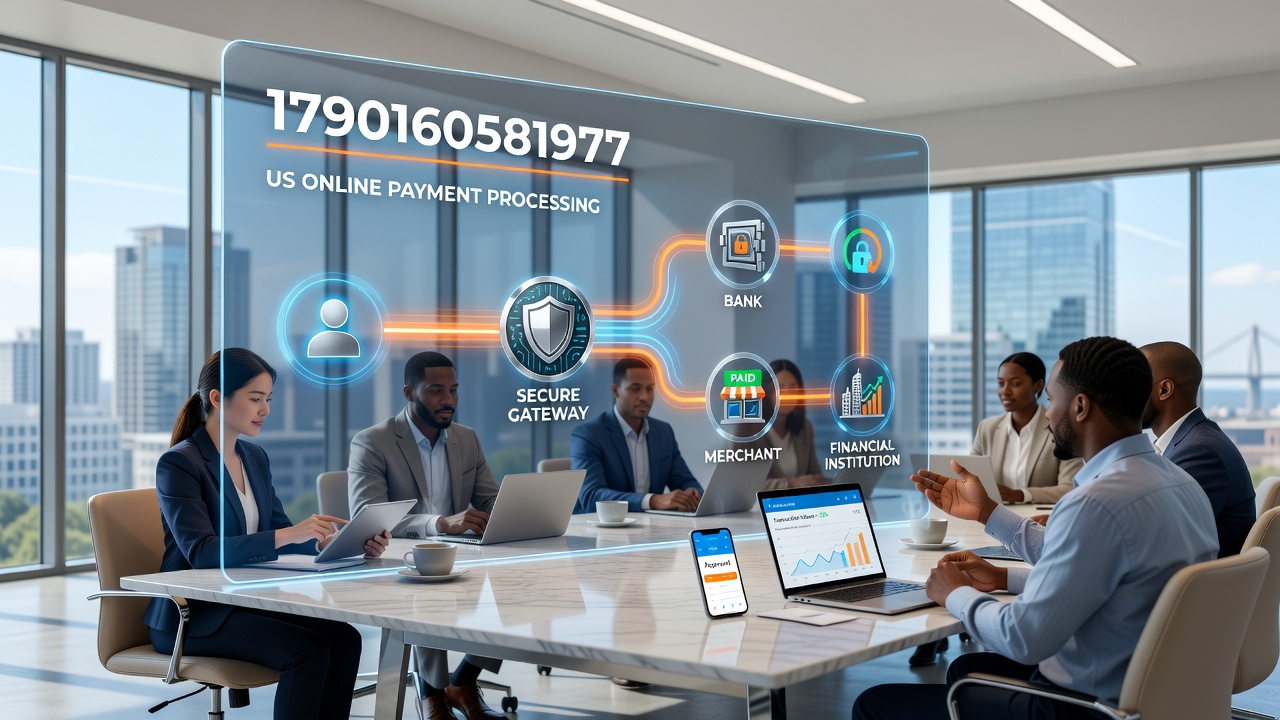 Merchants frequently pair gateway technology with automated tools that apply velocity checks and device fingerprinting, creating layered defenses without slowing down legitimate customer experiences. Data shows that platforms using these combined approaches report fewer disruptions during peak billing periods.
US online payment processing operates through interconnected networks that connect retailers, financial institutions, and consumers across digital storefronts, and these systems handle billions of transactions each year while maintaining security standards set by regulatory bodies and industry groups. Data from the Federal Reserve indicates that electronic payments continue to grow as the dominant method for e-commerce activity, with credit cards, ACH transfers, and digital wallets forming the core options available to merchants. Payment gateways serve as the initial interface that captures customer details and routes them through verification layers before funds move to merchant accounts. These gateways integrate with processors that communicate directly with card networks and banking systems, ensuring authorization happens within seconds for most transactions. Observers note that many platforms now incorporate tokenization to replace sensitive card data with unique identifiers, which reduces exposure during storage and subsequent billing cycles. ACH processing adds another layer for subscription-based models because it enables direct bank-to-bank transfers at lower costs than card networks, and this method proves especially useful for recurring revenue streams where merchants prioritize efficiency over instant settlement. Research from industry reports shows ACH volumes rising steadily in e-commerce as platforms align these transfers with fraud screening tools that check account validity before deductions occur.Compliance and Security Standards
PCI DSS requirements shape how US merchants store and transmit cardholder information, requiring encryption, access controls, and regular audits to maintain compliance levels. Those who manage high transaction volumes often work with providers that automate much of the technical setup, allowing businesses to focus on operations rather than infrastructure. Tokenization plays a central role here because it limits the amount of actual payment data retained on merchant servers, which aligns with guidelines from security standards organizations. As of September 2026, updates to data protection frameworks continue to influence how platforms handle cross-border elements within US-based operations, though the primary focus remains on domestic transaction flows and consumer protections already embedded in existing regulations.Fraud Prevention in Recurring Billing
Fraud controls integrate at multiple points throughout the payment flow, from initial card verification to ongoing monitoring of subscription patterns. Systems flag unusual activity such as mismatched billing addresses or rapid successive attempts, and these checks help merchants reduce chargebacks that can erode revenue. One study from a major research institution revealed that combining ACH with card processing allows businesses to diversify risk, since bank transfers carry different fraud profiles than credit transactions.
Merchants frequently pair gateway technology with automated tools that apply velocity checks and device fingerprinting, creating layered defenses without slowing down legitimate customer experiences. Data shows that platforms using these combined approaches report fewer disruptions during peak billing periods.