Tracing Data Pathways Between Credit Networks and Digital Sales Platforms to Enable Protected Periodic Collections for US-Based Online Operators
Uma Reed · Aug 6, 2026
Tracing Data Pathways Between Credit Networks and Digital Sales Platforms to Enable Protected Periodic Collections for US-Based Online Operators
US-based online operators rely on intricate data pathways that link credit networks directly to digital sales platforms, and these connections support protected periodic collections through structured verification steps at each transfer point. Researchers at academic institutions have mapped how authorization requests travel from merchant servers to card issuers via payment processors, with each hop carrying encrypted tokens that replace full account details. Data from the Federal Reserve Bank of New York indicates that recurring transaction volumes grew steadily through mid-2026, prompting platform operators to refine routing logic so that authorization messages reach the correct endpoints without exposing sensitive fields.
Core Components of Data Pathway Architecture
Pathway architecture begins at the checkout layer where customer details enter the system, then moves into a gateway that formats requests according to network specifications before they reach acquirers and issuers. Observers note that token service providers sit between these stages, generating unique identifiers that platforms store for future billing cycles while the actual card data remains in secure vaults managed by the networks. In August 2026 several major processors updated their endpoint configurations to accommodate new message formats that carry additional risk signals, allowing issuers to evaluate recurring requests against updated fraud models without increasing latency.
Digital sales platforms integrate these pathways through APIs that transmit standardized fields such as amount, frequency, and customer reference codes, and these fields travel alongside encrypted payloads that prevent interception during transit. Studies from the University of California, Berkeley have examined how endpoint authentication protocols reduce the surface area for unauthorized access, showing that platforms using mutual TLS connections experience fewer routing anomalies than those relying on single-factor verification.
Security Layers Along the Route
Security protocols activate at multiple junctions, beginning with point-to-point encryption that wraps data as it leaves the merchant environment and continuing through network-level monitoring that flags unusual patterns in periodic collection attempts. Those who manage large subscription fleets report that embedding device fingerprint data into each authorization request helps issuers distinguish legitimate repeat charges from compromised credentials. European Central Bank guidelines on payment service security, updated in early 2026, emphasize the need for dynamic linking of transaction data to specific collection schedules, a practice now mirrored in several US platform implementations.
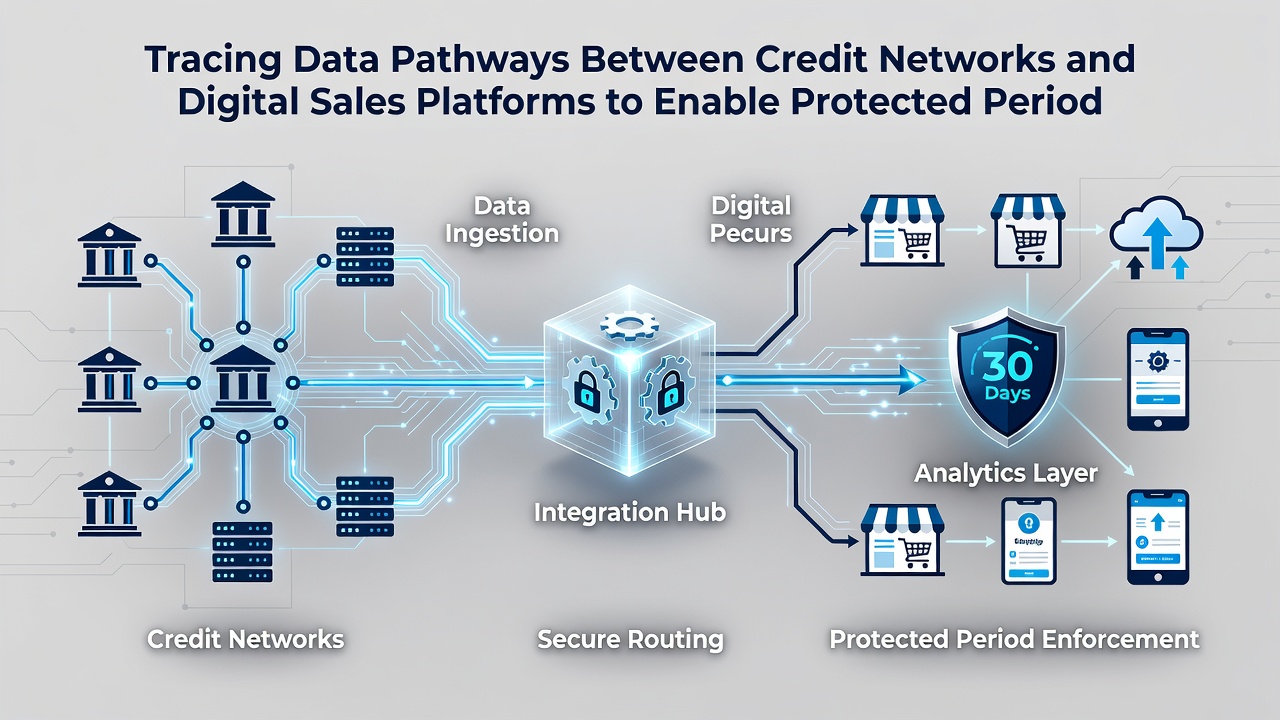
Token lifecycle management forms another critical segment of these pathways, where tokens are issued, rotated, and revoked according to network rules that prevent reuse after detected anomalies. Figures from industry reports reveal that platforms implementing automated token rotation every ninety days see measurable declines in failed collection attempts, because expired or flagged tokens trigger immediate re-verification before the next scheduled charge. Network operators maintain audit logs that trace each token's journey from issuance through every successful or declined collection, creating a chain of custody that regulators can review during compliance examinations.
Integration Points for Recurring Collections
Integration occurs when digital platforms schedule future collection events and embed the stored tokens into batch files that processors submit on predetermined dates. These batch submissions travel over dedicated lines that bypass public internet routes in many cases, reducing exposure while preserving the ability to receive real-time responses from issuers. Research published by the Bank of Canada in 2025 compared batch versus on-demand routing for recurring payments and found that scheduled pathways maintained higher success rates when accompanied by pre-notification messages sent to customers twenty-four hours in advance.
Platform operators coordinate with credit networks to align data schemas so that fields indicating subscription status, retry logic, and dunning sequences transmit without truncation or misinterpretation. When mismatches occur, collection attempts fail at the issuer level, and the resulting decline codes travel back along the same pathway to trigger platform-side actions such as updated payment method requests. Analysts tracking August 2026 transaction data observed that platforms using unified schema mappings reduced retry failures by noticeable margins compared with earlier fragmented approaches.
Monitoring and Compliance Mechanisms
Continuous monitoring systems sit at each junction to capture metrics on latency, error rates, and authorization success percentages, feeding these figures into dashboards that operations teams review daily. Regulatory frameworks administered by the Consumer Financial Protection Bureau require operators to maintain records of every data exchange involved in periodic collections, including timestamps and endpoint identifiers, for a minimum retention period. These records enable examiners to reconstruct the full pathway of any disputed charge and verify that encryption standards remained intact throughout the process.
Cross-border considerations arise when US operators serve international customers, requiring pathways to incorporate currency conversion nodes and additional verification layers mandated by destination country rules. Australian Securities and Investments Commission publications on digital payment resilience stress the importance of maintaining redundant routing options so that a single network outage does not interrupt scheduled collections. Platforms that incorporate these redundant paths report fewer service disruptions during peak billing windows.
Conclusion
Data pathways between credit networks and digital sales platforms continue to evolve as operators incorporate new encryption standards, token management practices, and monitoring tools that safeguard periodic collections for US-based online businesses. The documented growth in recurring transaction volumes through 2026 underscores the necessity of maintaining clear, auditable routes that preserve both security and operational efficiency at every stage of the journey.